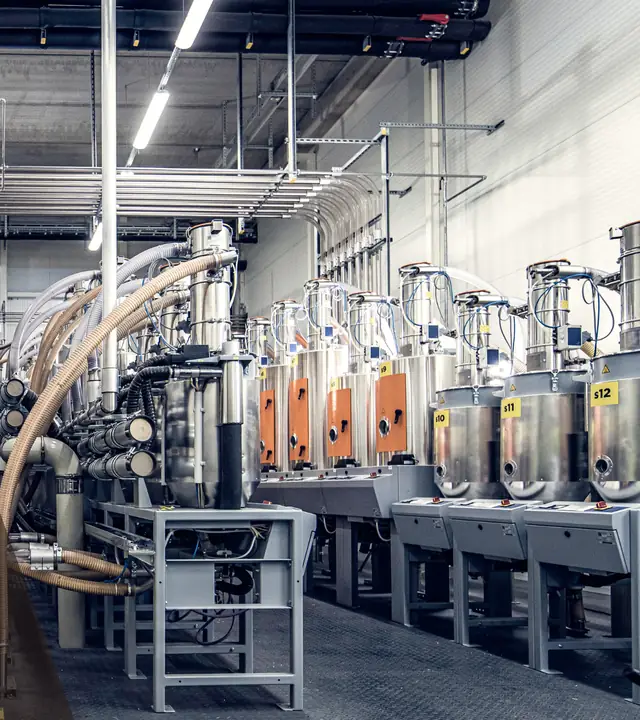
Plant & Machinery Valuation
Industrial plants, machinery and equipment — for bank finance, insolvency proceedings, financial reporting and tax.
Learn more
Valuation of a company's fixed and specialised assets for its balance sheet, lenders, auditors, tribunals and transactions — by IBBI Registered Valuers in each asset class.
Overview
Companies need independent valuations of their assets at many points: when they revalue fixed assets in their accounts, raise or restructure debt, merge or demerge, enter a joint venture, face insolvency proceedings, or settle a dispute.
These assignments often cover several asset classes at once — land and buildings, plant and machinery, and sometimes securities or financial assets. Under the Companies Act, 2013 such valuations must be done by registered valuers for each asset class.
Our team includes IBBI Registered Valuers for Land & Building, Plant & Machinery and Securities or Financial Assets, so a multi-asset assignment can be handled by one team under consistent assumptions.
Purposes
Fair value measurement and revaluation of property, plant and equipment under Ind AS, and impairment testing support.
Financial reporting
Fair value and liquidation value of a corporate debtor's assets for resolution professionals and committees of creditors.
Insolvency (IBC)
Asset valuation for mergers, amalgamations, demergers, slump sales, takeovers and joint ventures.
Mergers & restructuring
Security valuation for lenders, and valuation for loan recovery, DRT proceedings and auctions.
Loans & recovery
Valuation under the Income-tax Act and for stamp duty adjudication on transfers.
Tax & stamp duty
Arbitration, litigation support and land acquisition compensation.
Disputes
Scope
Checklist
Our process
Step 01
We agree the purpose, valuation date, standard of value and the asset classes in scope.
Step 02
We reconcile the fixed asset register with the books and identify assets for physical verification.
Step 03
Engineers inspect land, buildings and plant at each location.
Step 04
Each asset class is valued by the registered valuer for that class, using consistent assumptions.
Step 05
Results are reconciled across classes and reviewed before issue.
Step 06
Asset-wise schedules and a report in the form required by the auditor, tribunal or lender.
Who does the work
Registered valuers, chartered engineers and specialists who work on corporate valuation assignments.
Sharadkumar B. Chalikwar
Chairman & Managing Director
IBBI — Land & BuildingIncome Tax — Land & Building, Plant & MachineryIOV — Land & BuildingIIV — Plant & MachineryPVAI — Land & BuildingChartered Engineer (India) — The Institution of Engineers (India)Fellow — The Institution of Engineers (India)
Manoj B. Chalikwar
Joint Managing Director
IBBI — Land & Building, Plant & MachineryIncome Tax — Land & Building, Plant & MachineryIIV — Land & Building, Plant & MachineryPVAI — Land & BuildingIIV-RVF — Plant & MachineryChartered Engineer (India) — The Institution of Engineers (India)Licensed Structural Engineer — Maharashtra (UDCPR) — Directorate of Town Planning, Government of MaharashtraMember — The Institution of Engineers (India)
Vidhi M. Chalikwar
Director
Income Tax — Land & BuildingIIV — Land & BuildingIIV-RVF
Umang A. Patel
Director
IBBI — Land & Building, Plant & MachineryIncome Tax — Land & Building, Plant & MachineryIIV — Land & Building, Plant & MachineryIIV-RVF — Land & Building, Plant & MachineryChartered Engineer (India) — The Institution of Engineers (India)Associate Member — The Institution of Engineers (India)
Shashikant B. Chalikwar
Executive Director
Income Tax — Land & BuildingIIV — Land & BuildingIIV-RVF — Land & BuildingChartered Engineer (India) — The Institution of Engineers (India)Member — The Institution of Engineers (India)
Avinash Pandey
Regional Head, Thane
IBBI — Plant & MachineryIncome Tax — Plant & MachineryIIV-RVF — Plant & MachineryChartered Engineer (India) — The Institution of Engineers (India)Member — The Institution of Engineers (India)
FAQ
Can't find the answer? Ask us directly — we're happy to explain how an assignment would work.
All questionsSection 247 of the Companies Act, 2013 requires valuations under the Act to be done by a registered valuer — a valuer registered with IBBI for the relevant asset class.
Yes. Our team includes IBBI Registered Valuers for Land & Building, Plant & Machinery and Securities or Financial Assets.
This page covers the valuation of a company's assets. Valuation of shares or the business as a whole falls under the Securities or Financial Assets class; ask us and we will tell you who in our team handles it.
Related services
Industrial plants, machinery and equipment — for bank finance, insolvency proceedings, financial reporting and tax.
Learn more
Land, buildings and projects — residential, commercial, industrial and redevelopment — for lenders, courts and tax.
Learn more
Independent assessment of a project's technical feasibility, cost, means of finance and financial viability for lenders.
Learn moreContact us
Take the first step — tell us about the asset or project and we'll take care of the rest.
Head office
Other offices
Thane · Pune · Nashik · Chhatrapati Sambhajinagar · Nanded · Indore · Ahmedabad · Rajkot · Delhi NCR
Call
A few details help us send an accurate proposal the first time. Fields marked * are required.