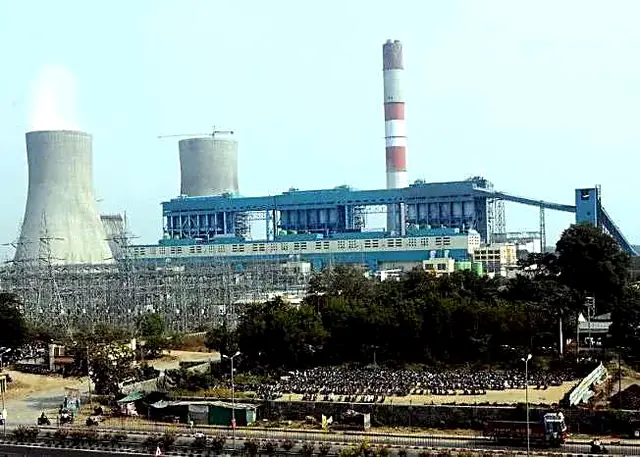
Power plants (thermal, solar, gas turbine)
Power Sector Valuation
Fixed-asset valuation of three power stations for MAHAGENCO
Chandrapur, Dhule and Uran, Maharashtra

Valuation of industrial plants, machinery and equipment by IBBI Registered Valuers (Plant & Machinery) — for lenders, insolvency professionals, corporates and auditors across India.
Overview
Plant and machinery valuation estimates the value of a business's movable fixed assets — production lines, process equipment, utilities, material-handling systems, tools, vehicles and specialised assets. Unlike land and buildings, machinery is valued by understanding what it does, how it has been maintained and how the market for similar equipment behaves.
The same machine can carry different values depending on the premise of value: in continued use as part of a working plant, for removal and sale elsewhere, or in a forced or orderly liquidation. Our reports state the premise, the basis of value and the approach used, so lenders, courts and auditors can rely on them.
Assignments are carried out and signed by valuers registered with the Insolvency and Bankruptcy Board of India for the Plant & Machinery asset class, supported by chartered engineers and site engineers who inspect every asset.
Purposes
Primary and collateral security valuation for term loans, working capital and refinancing, including periodic revaluation.
Bank finance
Fair value and liquidation value of a corporate debtor's plant and machinery during the insolvency resolution process.
Insolvency (IBC)
Valuation for reserve price fixation, auction and recovery proceedings before DRT and under SARFAESI.
Recovery & SARFAESI
Fair value and revaluation of fixed assets for Ind AS and audit purposes, and purchase price allocation.
Financial reporting
Reinstatement and replacement values to set sums insured, and assessments after loss or damage.
Insurance
Mergers, demergers, slump sales, joint ventures, asset transfers and sale of surplus or obsolete machinery.
Transactions & restructuring
Scope
Checklist
The exact list depends on the purpose; we confirm it at the start.
Methodology
We use the approach — or combination — that suits the asset, the purpose and the evidence available, and explain the choice in the report.
Current replacement or reproduction cost of a similar new asset, less physical deterioration and functional and economic obsolescence. The usual approach for specialised or installed plant.
Cost approach
Comparison with recent sales and quotations for similar used equipment, adjusted for age, condition, capacity and specification.
Market approach
Value derived from the income or cost savings the asset generates — used selectively, for example for revenue-generating plants.
Income approach
Our process
Step 01
We agree the purpose, basis of value, premise and valuation date with you or the appointing bank.
Step 02
We review the fixed asset register, invoices, technical specifications and maintenance records.
Step 03
Our engineers physically verify each asset, record nameplate details, condition and utilisation, and photograph it.
Step 04
We assess remaining useful life and obsolescence and research current replacement costs and second-hand prices.
Step 05
We apply the appropriate approaches and reconcile them to a value conclusion for each asset or group.
Step 06
A signed report in the format required by the bank, IBBI or the auditor, with asset-wise schedules and photographs.
Who does the work
Registered valuers, chartered engineers and specialists who work on plant & machinery valuation assignments.
Sharadkumar B. Chalikwar
Chairman & Managing Director
IBBI — Land & BuildingIncome Tax — Land & Building, Plant & MachineryIOV — Land & BuildingIIV — Plant & MachineryPVAI — Land & BuildingChartered Engineer (India) — The Institution of Engineers (India)Fellow — The Institution of Engineers (India)
Manoj B. Chalikwar
Joint Managing Director
IBBI — Land & Building, Plant & MachineryIncome Tax — Land & Building, Plant & MachineryIIV — Land & Building, Plant & MachineryPVAI — Land & BuildingIIV-RVF — Plant & MachineryChartered Engineer (India) — The Institution of Engineers (India)Licensed Structural Engineer — Maharashtra (UDCPR) — Directorate of Town Planning, Government of MaharashtraMember — The Institution of Engineers (India)
Umang A. Patel
Director
IBBI — Land & Building, Plant & MachineryIncome Tax — Land & Building, Plant & MachineryIIV — Land & Building, Plant & MachineryIIV-RVF — Land & Building, Plant & MachineryChartered Engineer (India) — The Institution of Engineers (India)Associate Member — The Institution of Engineers (India)
Avinash Pandey
Regional Head, Thane
IBBI — Plant & MachineryIncome Tax — Plant & MachineryIIV-RVF — Plant & MachineryChartered Engineer (India) — The Institution of Engineers (India)Member — The Institution of Engineers (India)
FAQ
Can't find the answer? Ask us directly — we're happy to explain how an assignment would work.
All questionsUnder the Companies Act and the Insolvency and Bankruptcy Code, valuations of a corporate debtor's assets must be carried out by valuers registered with IBBI for the relevant asset class. Our Plant & Machinery valuers hold IBBI registrations, which you can verify on the IBBI register.
Fair value assumes an orderly sale between willing parties with adequate marketing. Liquidation value assumes the asset must be sold quickly, often piecemeal and without full marketing, and is usually lower. IBC valuations report both.
Yes. Physical verification of each asset is part of every assignment; values are not based on the asset register alone.
It depends on the number of assets and locations. A single-site plant is typically inspected within days of appointment, with the report following once documents are complete.
Case studies
How plant & machinery valuation assignments have run in practice — from our assignment records, anonymised where the client has not agreed to be named.
All case studiesPower Sector Valuation
Chandrapur, Dhule and Uran, Maharashtra
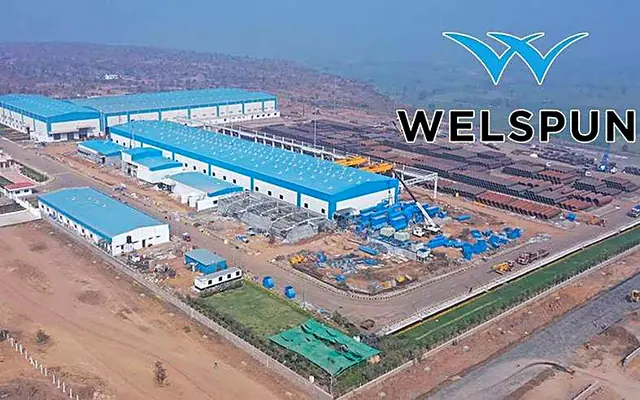
Lender's Independent Engineer
Anjar, Kachchh district, Gujarat
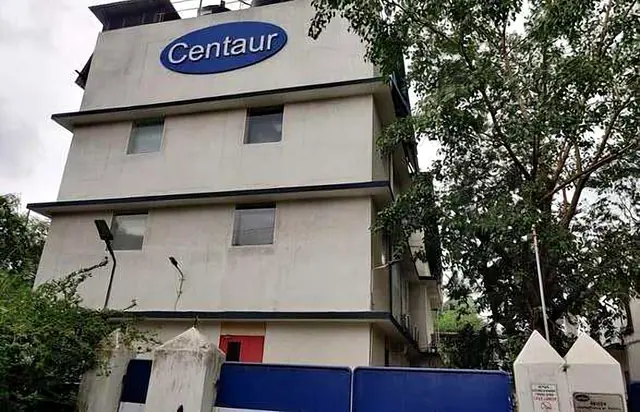
Plant & Machinery Valuation
Pune, Raigad and Palghar districts (Maharashtra); South Goa; Vadodara and Valsad districts (Gujarat); Solan district (Himachal Pradesh)
Related services
Land, buildings and projects — residential, commercial, industrial and redevelopment — for lenders, courts and tax.
Learn more
A company's land, buildings, plant and other assets — for financial reporting, insolvency, mergers, loans and tax.
Learn more
Marine vessels, helicopters, port cranes and other specialised equipment.
Learn moreContact us
Take the first step — tell us about the asset or project and we'll take care of the rest.
Head office
Other offices
Thane · Pune · Nashik · Chhatrapati Sambhajinagar · Nanded · Indore · Ahmedabad · Rajkot · Delhi NCR
Call
A few details help us send an accurate proposal the first time. Fields marked * are required.